
Wind Damage Insurance Claims
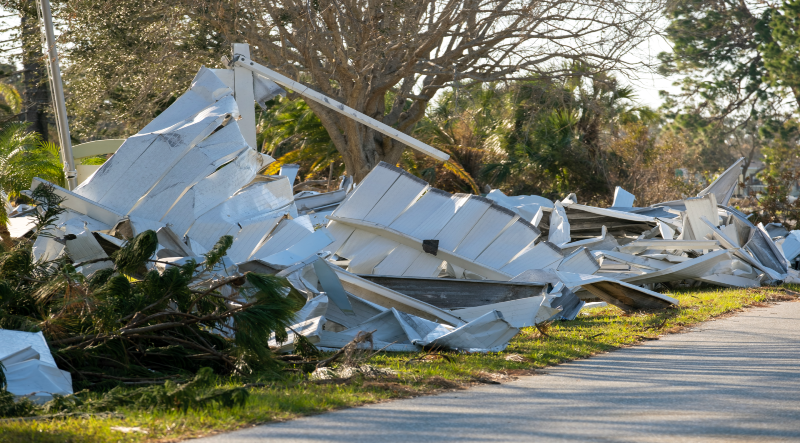
Wind Damage Insurance Claims Across Massachusetts: Licensed Public Adjusters
Why Wind Does So Much Damage to Massachusetts Properties
Massachusetts sits in the path of a remarkable range of wind events, and each one attacks a building differently. The conditions driving wind damage claims across the Commonwealth include:
- Nor’easters that combine sustained high winds with driving rain, forcing water through any opening the wind creates
- The remnants of tropical systems and hurricanes that track up the coast and reach deep inland with damaging gusts
- Coastal winds off the Atlantic that batter exposed properties from Cape Cod to the North Shore with little to slow them down
- Sudden convective storms and microbursts that concentrate destructive force on a small area in minutes
- Winter windstorms that combine with snow and ice loads to tear at roofing and siding already stressed by the cold
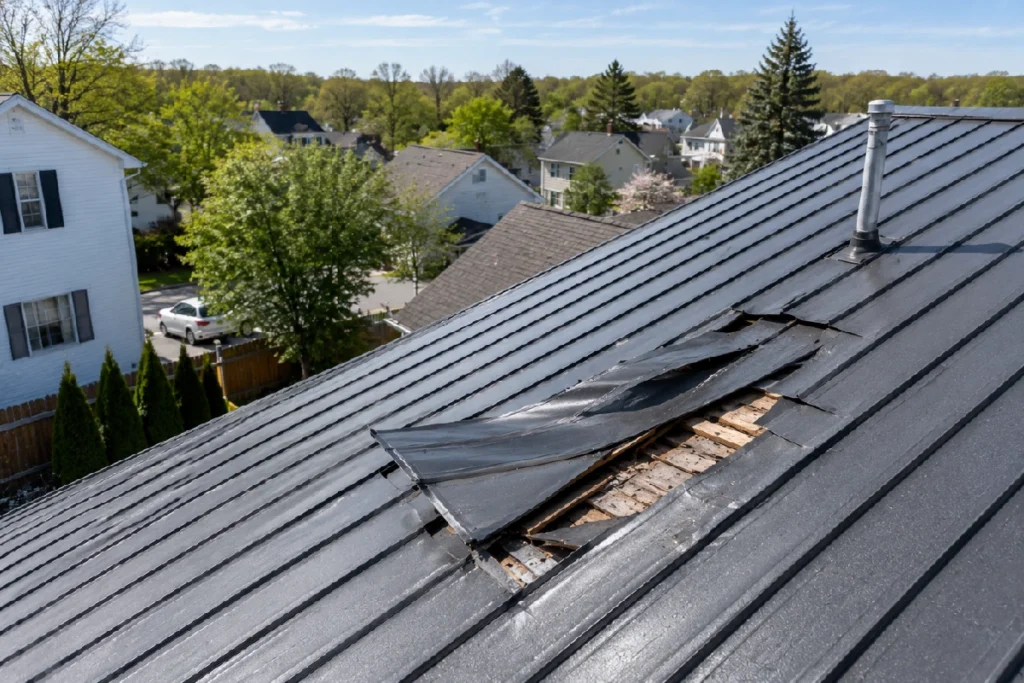
Wind rarely stops at one system. It commonly lifts roofing to the point of a full Massachusetts roof damage claim, and the same gusts bring down the trees behind many fallen tree damage claims in Massachusetts.
How Massachusetts Insurers Reduce Wind Damage Claims
They Call It Wear and Tear
The most common tactic on Massachusetts wind claims is reclassifying storm damage as gradual deterioration. Lifted shingles, loosened flashing, and cracked siding all get attributed to age rather than a specific wind event, which moves the loss outside coverage. Countering this requires documentation that ties the damage to a datable storm rather than the passage of time.
They Exclude the Interior Water Damage
Wind’s real cost often shows up inside, where rain driven through a wind-created opening ruins ceilings, walls, insulation, and belongings. Massachusetts insurers frequently treat that interior damage as a separate, non-covered issue, severing it from the wind event that actually caused it. We document the connection from the exterior breach to the interior loss so the whole chain stays in the claim.
They Approve Partial Repairs on Full-Slope Damage
When wind lifts shingles across an entire roof slope, carriers often approve replacing only the visibly missing pieces. Between shingle matching problems and Massachusetts code requirements, that partial fix usually fails to restore the roof, but insurers authorize it because it costs less. We build the case for complete repair or replacement where a patch would leave the property exposed.
They Settle Before the Hidden Damage Surfaces
Wind damage to the building envelope frequently stays hidden until the next rain reveals a leak or moisture works its way into the structure. Massachusetts insurers push for fast settlement precisely to close the claim before that hidden damage appears. We inspect thoroughly up front and document the full scope so nothing gets left for you to pay later.
Fees
With a Public Adjuster, there are no fees or upfront costs until we receive an agreed settlement. We charge up to 10% of the claim which is regulated by the Division of Insurance. We believe everyone should have quality representation. That’s why we work on a contingency-fee basis, which means you only pay us when all parties are made whole.
Please reach out for a risk free inspection & consultation
What Marinilli Adjusters Does Differently for Massachusetts Wind Claims
We Inspect the Entire Building Envelope
Our inspections cover the roof, siding, flashing, windows, and every point where wind can breach the weather barrier, along with the interior spaces where water travels next. We document the visible damage and the vulnerabilities behind it, giving your claim a complete foundation instead of a surface snapshot.
We Price Against Real Massachusetts Costs
Our repair estimates use actual Massachusetts labor and material rates rather than the national pricing databases carriers use to understate cost. Every figure reflects what the work genuinely costs in your part of the Commonwealth, which makes our numbers far harder for an insurer to dispute.
We Read Your Full Policy Before Negotiating
Before engaging your carrier, we analyze your Massachusetts homeowner or commercial policy in full, identifying wind and named-storm deductibles, replacement cost provisions, ordinance or law coverage for code upgrades, interior and contents coverage, and additional living expenses. These provisions routinely go unclaimed when owners handle wind claims alone.
We Handle the Insurer From Start to Finish
From first notice of loss through final settlement, we manage every inspection, document request, and negotiation with your carrier. You are not decoding adjuster reports, weighing lowball offers without context, or facing pressure to sign before your full wind damage is documented.
Massachusetts Property Types We Represent
Single-Family Homeowners
Roofing material, siding type, building age, and exposure all shape how wind damage is assessed and what your policy owes. We understand how those variables play out in a Massachusetts wind claim, from a coastal Cape home to an inland Colonial.
Triple-Deckers and Multi-Family Buildings
Massachusetts has one of the densest concentrations of triple-deckers in the country, and their tall, exposed profiles take heavy wind punishment. When damage crosses unit lines, we manage the documentation and coordination these multi-family claims require.
Condo Associations and HOAs
Shared roofs and exterior walls under a master policy raise coverage questions individual owners and boards rarely have the tools to resolve. We work with Massachusetts condo associations and HOA managers to document wind losses and recover fully under the governing master policy.
Commercial Properties
Wind uplift on flat commercial roofs, damaged signage, broken glazing, and compromised building envelopes bring losses that reach well beyond the obvious. We represent Massachusetts commercial property owners through wind claims covering structural damage, interior loss, and business interruption where it applies.
Who We Help
Single-Family Homeowners
Roofing material, siding type, building age, and exposure all shape how wind damage is assessed and what your policy owes. We understand how those variables play out in a Massachusetts wind claim, from a coastal Cape home to an inland Colonial.
Triple-Deckers and Multi-Family Buildings
Massachusetts has one of the densest concentrations of triple-deckers in the country, and their tall, exposed profiles take heavy wind punishment. When damage crosses unit lines, we manage the documentation and coordination these multi-family claims require.
Condo Associations and HOAs
Shared roofs and exterior walls under a master policy raise coverage questions individual owners and boards rarely have the tools to resolve. We work with Massachusetts condo associations and HOA managers to document wind losses and recover fully under the governing master policy.
Commercial Properties
Wind uplift on flat commercial roofs, damaged signage, broken glazing, and compromised building envelopes bring losses that reach well beyond the obvious. We represent Massachusetts commercial property owners through wind claims covering structural damage, interior loss, and business interruption where it applies.
Why Hire a Public Adjuster for Your Massachusetts Wind Damage Claim
You Get an Assessment Built for Your Side of the Claim
Your insurer’s adjuster inspects with the carrier’s interests in mind, and wind damage is easy to underscope. We inspect the same property to establish what you are actually owed, capturing the hidden envelope and interior damage their assessment tends to skip, and building a record made to support your claim.
You Recover More of What the Loss Actually Costs
Wind claims are underpaid far more often than overpaid, through wear-and-tear reclassification, excluded interior damage, and partial repairs. We counter each with documentation and Massachusetts pricing that moves the settlement toward the true cost of making your property whole.
You Hand Off the Time and the Pressure
A wind damage claim in Massachusetts means inspections, estimates, adjuster meetings, paperwork, and negotiation, all while you are living with a damaged property. We take the entire process off your plate and deal with the carrier directly, so you are not learning claims procedure under pressure.
You Gain Local Knowledge the Carrier Can’t Dismiss
Frequently Asked Questions About Roof Damage Claims in Rhode Island
Rhode Island Communities We Serve
- Boston
- Worcester
- Springfield
- Lowell
- Cambridge
- Brockton
- New Bedford
- Quincy
- Lynn
- Fall River
- Newton
- Somerville
- Lawrence
- Framingham
- Plymouth